DayOne files for a Nasdaq IPO with 962 MW in service
Data center operator DayOne filed for a Nasdaq IPO as DODC. It has 962 MW in service and needs about $11.4B to build the 2,281 MW it has already booked.
3 min read
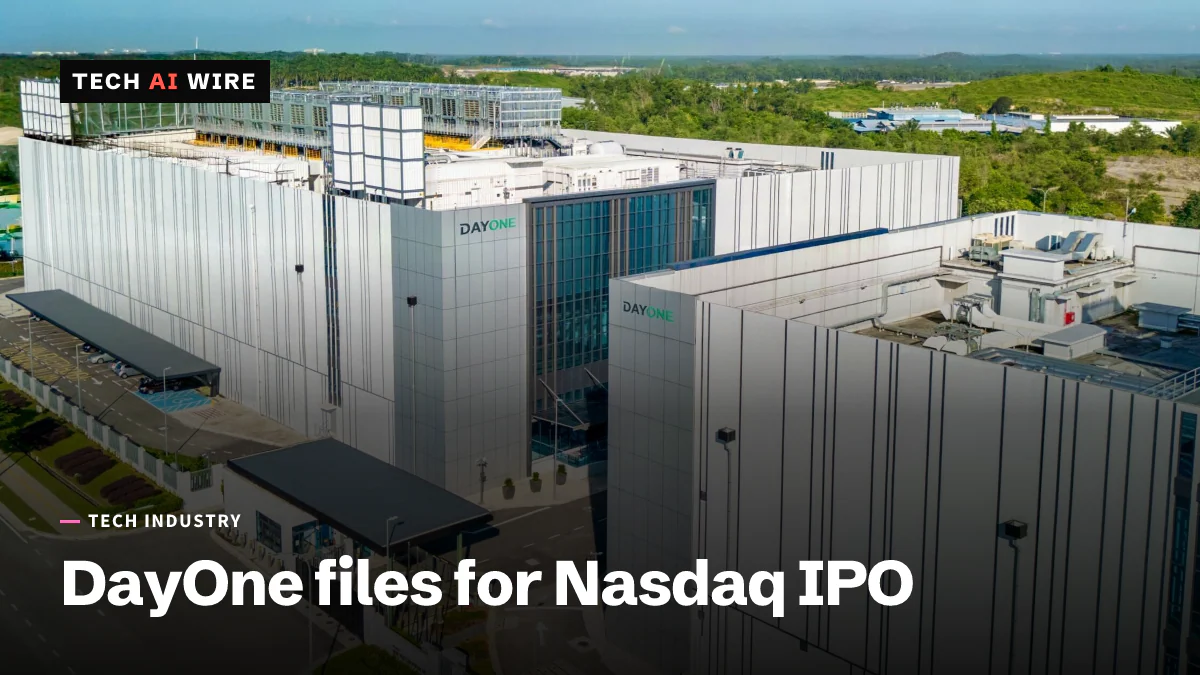
By the numbers
- in service, with 1,328 MW under construction
- 962 MW
- capital spending needed to finish booked capacity
- $11.4B
- of first-half revenue from one customer
- 69.2%
- revenue in the first half of 2026
- $512M
DayOne Data Centers, a Singapore-based builder of large data centers for cloud and AI companies, filed for a Nasdaq listing under the ticker DODC on October 5, 2026. Its F-1 prospectus shows 962 megawatts of capacity in service and another 1,328 MW under construction. It also shows how much that growth depends on very few buyers: one customer brought in 69.2% of revenue in the first half of 2026. The filing gives a rare look at the money behind AI data centers in Asia-Pacific and Europe.
What DayOne is
DayOne builds and runs hyperscale data center campuses. "Hyperscale" means very large sites rented by the biggest cloud and technology companies. The company calls itself "a leading digital infrastructure platform outside of the United States and China."
It used to be part of GDS Holdings, another data center company. The filing says GDS stopped consolidating it, meaning it no longer counted DayOne in its own accounts, on December 31, 2024. The company was renamed DayOne on January 1, 2025, from DigitalLand Holdings Limited.
Renaissance Capital, which tracks new listings, lists its markets as Malaysia, Indonesia, Singapore, Thailand, Japan, Finland and Spain. The filing says DayOne holds about 33% of the market in the region it calls SIJORI: Singapore, Johor in Malaysia, and Batam in Indonesia.
The numbers in the filing
| Measure | Figure | Period or date |
|---|---|---|
| Capacity in service | 962 MW | September 20, 2026 |
| Under construction | 1,328 MW | September 20, 2026 |
| Contracted bookings | 2,281 MW | per the filing |
| Revenue | $512.0 million | First half of 2026 |
| Net loss | $77.2 million | First half of 2026 |
| Adjusted EBITDA | $205.9 million (40.2% margin) | First half of 2026 |
| Total debt | $4.9 billion | June 30, 2026 |
| Cash | $2.0 billion | June 30, 2026 |
| Net loss | $367.1 million | 2025 |
Adjusted EBITDA is profit before interest, taxes, depreciation and some other costs. Data center companies use it because their buildings lose value on paper for years, which pushes reported profit down.
Renaissance Capital puts revenue for the 12 months to June 30, 2026 at $845 million. It counts 4.6 gigawatts of capacity in total, adding land with secured power to the built and building sites.
How much it needs to spend
The biggest figure is the cost of finishing what customers have already signed for. DayOne estimates about $11.4 billion of capital spending to complete its 2,281 MW of bookings.
The filing does not give a price range or the number of shares yet. Renaissance Capital estimates the offering at $3.0 billion. The lead underwriters are Morgan Stanley, J.P. Morgan, BofA Securities, Citigroup and BNP Paribas.
The customer risk
Contracts usually run 10 to 15 years with renewal options, the filing says. Seven hyperscale customers have each committed to more than 200 MW across several markets.
But revenue is concentrated. The largest customer made up 69.2% of first-half revenue and the second largest 15.1%. The filing names this as a risk: "if any major customer reduces demand for our services, we may have difficulty in replacing that demand."
DayOne also claims a cost edge. It says it delivers capacity "within 12 months" at costs "around 20% to 30% below industry average," with a "development yield of around mid-teens."
What this means for developers
- AI capacity is spreading beyond the usual regions. Large campuses in Asia-Pacific and Europe give cloud providers more room to add GPU regions there. Teams serving users in those areas may see new low-latency options.
- Power and build time, not chips, set the pace. DayOne's pitch is delivery "within 12 months." For anyone waiting on capacity, the date a building gets power matters as much as the GPU order.
- Concentration cuts both ways. When one buyer takes 69.2% of a supplier's revenue, that buyer's plans shape where capacity appears. Smaller cloud customers end up downstream of those decisions.
- Watch the final prospectus. The price range, and how DayOne plans to pay for its $11.4 billion build plan, will show how much growth public investors are willing to fund.
DayOne's listing will test how public investors value an AI data center builder that works outside the US and China.
Sources
- DayOne Data Centers Ltd - Form F-1 - U.S. SEC
- Global data center developer DayOne Data Centers files for an estimated $3.0 billion US IPO - Renaissance Capital
Related articles
Micron sees tighter memory supply in 2027 and 2028
Micron posted $54.23 billion in fiscal Q4 revenue and guided to $61.5 billion, then warned memory supply will be tighter in 2027 and 2028 than in 2026.
Firmus pulls $5 billion IPO, turns to private investors
Nvidia-backed Firmus pulled its US$5 billion IPO on October 9, citing volatility. It had sought a US$30.6 billion value, triple its August round.
Wood Mackenzie: batteries beat gas peakers in 43 markets
Four-hour batteries now cost less than open-cycle gas peakers in all 43 markets Wood Mackenzie modeled. Solar is the cheapest new power in 43 of 48.
The weekly digest
One email every Friday with the week's top stories from all six desks: AI, dev tools, coding, the tech industry, startups and what's next. Free, no spam.